

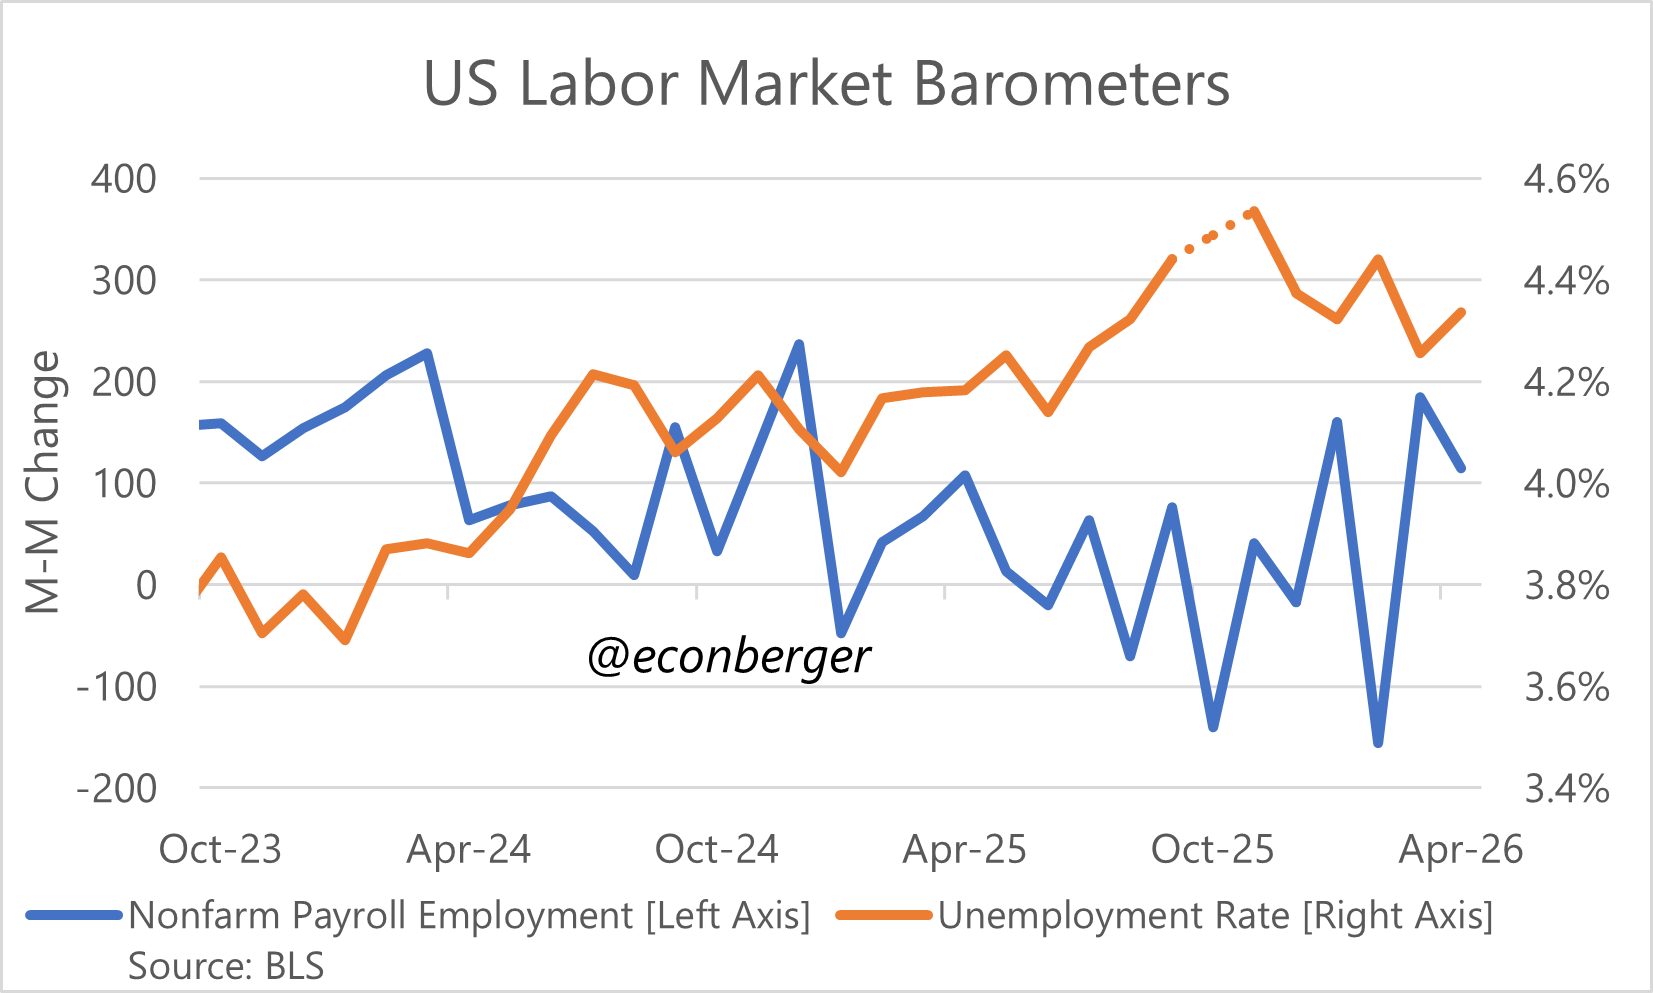
TL;DR: April’s jobs report was a good, not great one. We experienced the 2nd consecutive large gain in nonfarm payroll employment, but household survey data were a little weaker than in March. Overall, the job market is off to a good start in the first 4 months of 2026.
Key stats:
Unemployment Rate: Rose by 0.08pp to 4.33% (mildly bad)
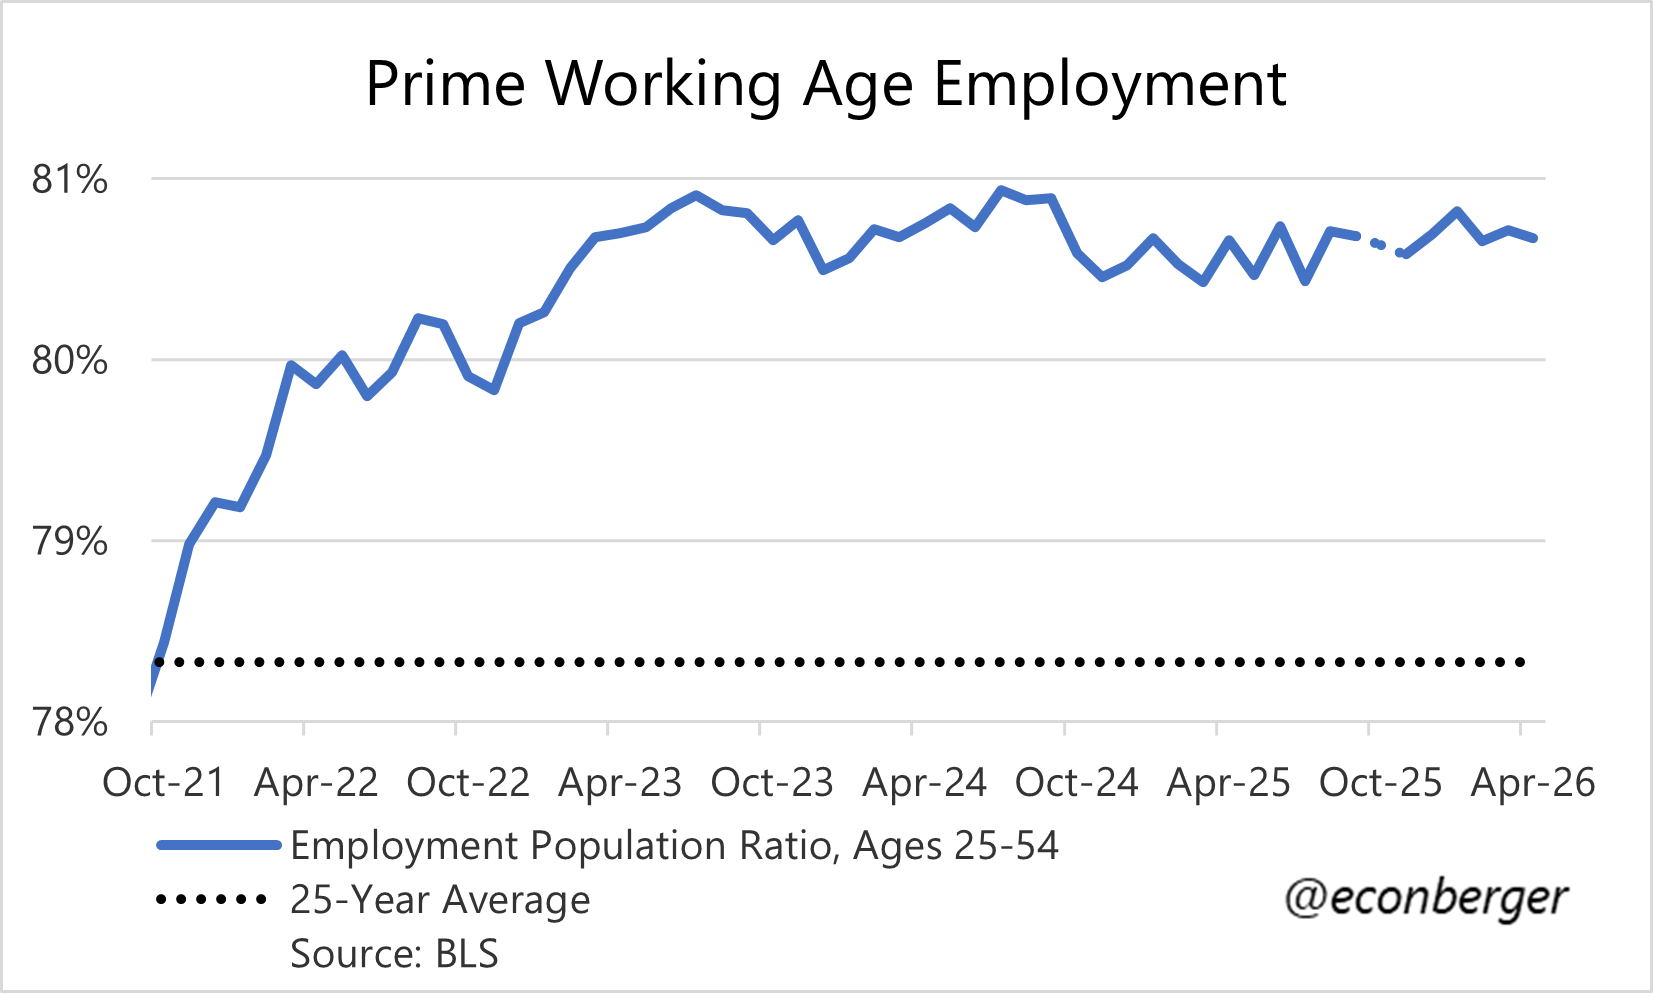
Prime Working Age Employment-Population Ratio: Fell by 0.5pp to 80.67% (mildly bad)
Nonfarm Payroll Employment: +115K (very good)
This recap includes:
The Big Picture
Data Rundown
More below chart.
1. The Big Picture
My 2026 labor market outlook included a range of scenarios with probabilities conveniently attached to them. Four months into 2026, we’re tracking somewhere between my 60th and 80th percentile scenarios - i.e. the job market is doing slightly better than I expected.
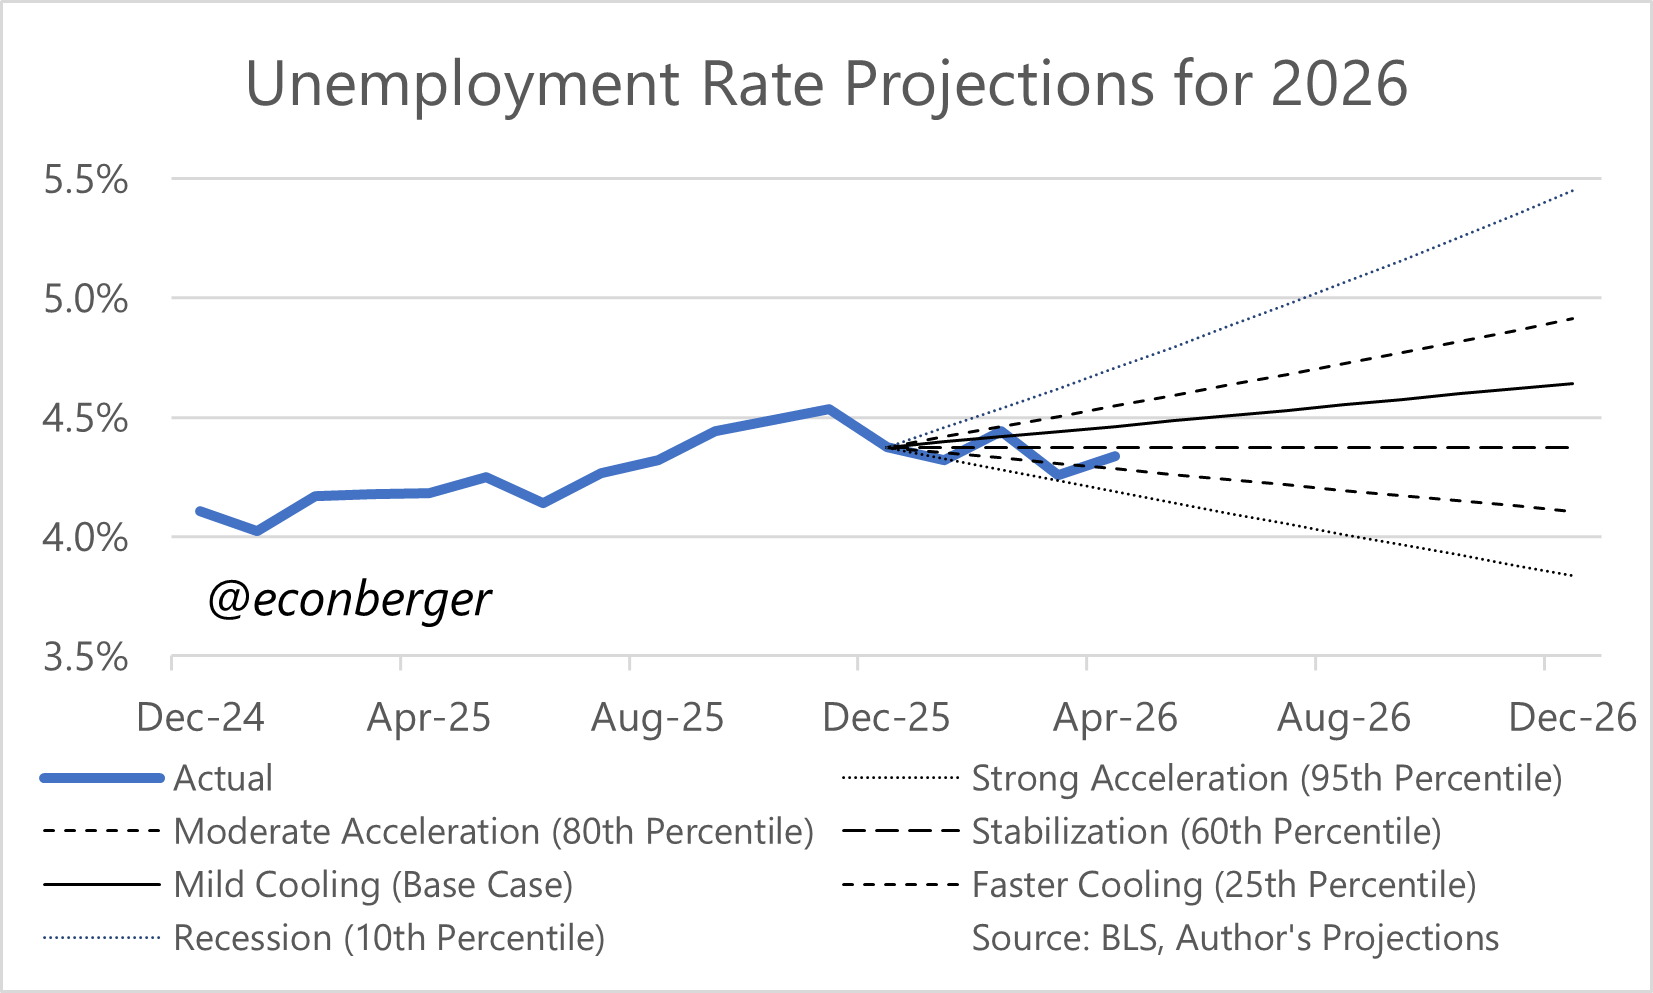
Today’s jobs report was good, not great. We saw a second consecutive triple-digit gain in nonfarm payroll employment, which I’d characterize as very good1; the household survey portion of the report was mildly weaker than in April than March. But we saw enough positive data from other sources during April that I trust the NFP data’s upbeat vibe. And even with the softer household survey data, once you look past month-to-month noise, the cooling trajectory of late 2025 has stopped (and arguably slightly reversed).
And yet:
We have an ongoing Hormuz Strait closure that’s already leading to higher US energy prices. It’s way too early an aggregate labor market impact, but at some point those higher prices will start to hurt. Businesses squeezed by weaker consumer spending growth and higher production costs will dial back their headcount plans via some combination of less hiring and more layoffs.
Barring a quick Hormuz reopening that leads to lower prices, the green shoots of 2026 labor market recovery will wilt, though a renewed mild deterioration in the labor market (a la 2023, 2024 and 2025) is more likely than full-blown recession. There’s unfortunately still time to get to the top half of my fan chart.
2. Data Rundown
Let’s start with the establishment survey. A lot of takes today conveniently ignored February’s abysmal decline and focused on just the March/April gains. But 76K averaged over the first 4 months of the year is pretty solid - comfortable over what most people believe the breakeven rate to be. If we’re lucky enough to keep that pace up over the rest of the year, the unemployment rate will fall at least a little. As stated earlier, I don’t think we’ll be that lucky.2
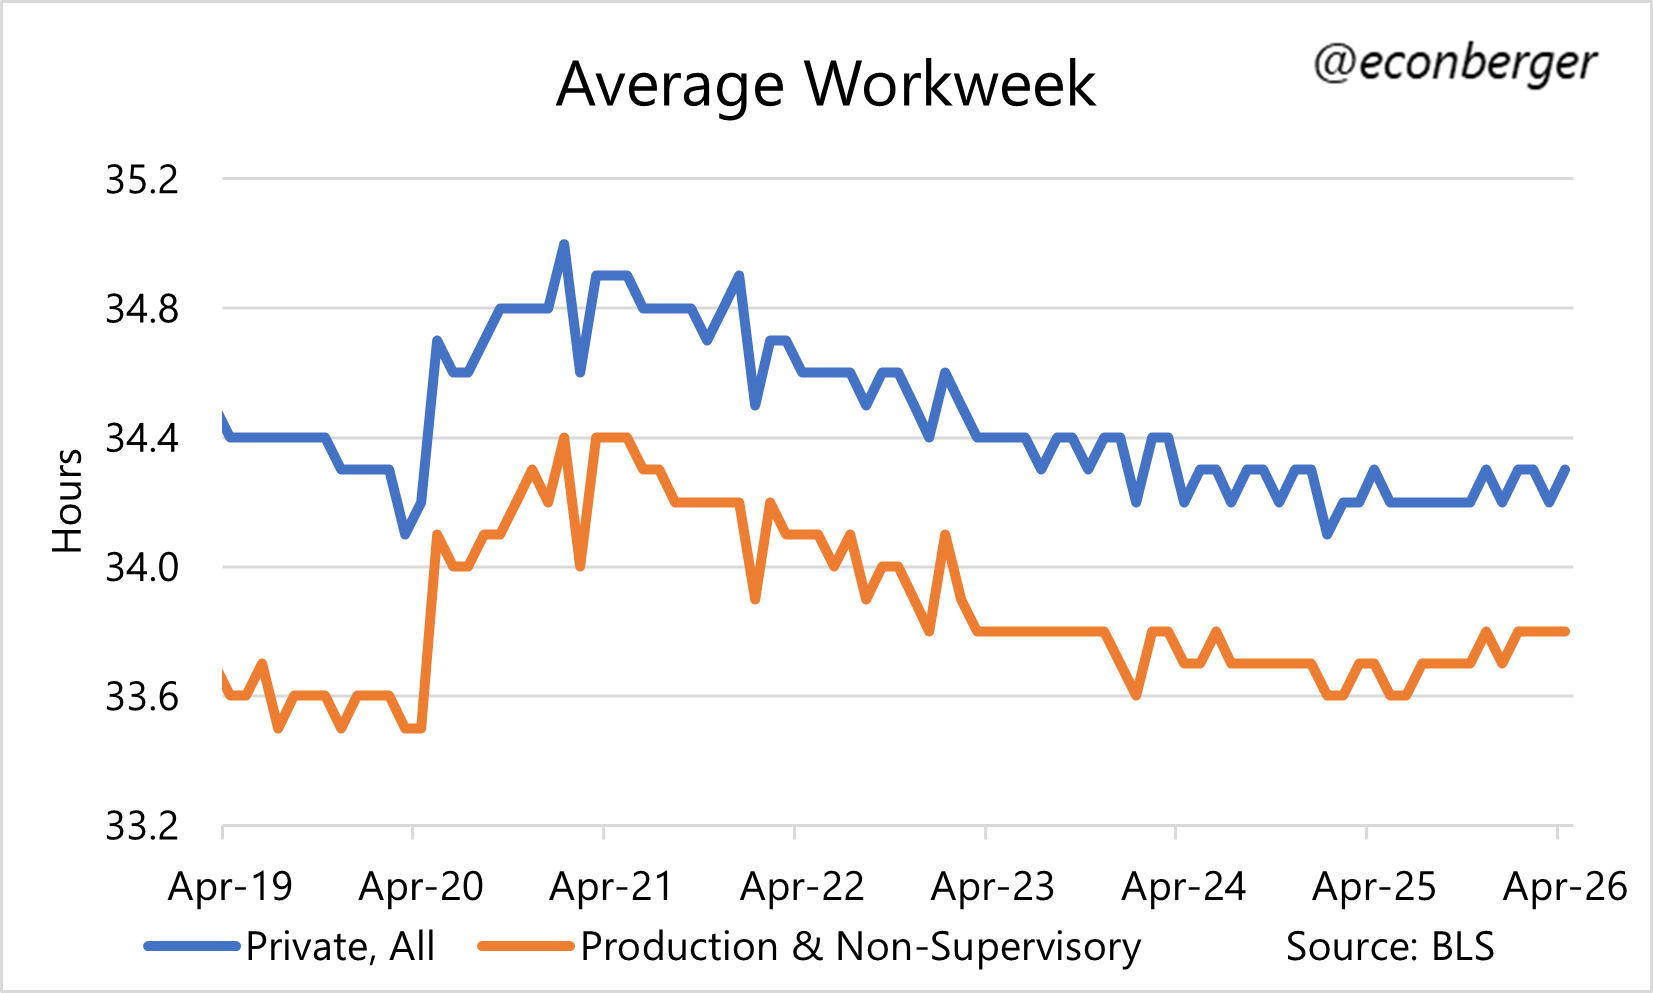
We’ve also seen a small increase in the average workweek; this is, in my opinion, a positive labor market signal.
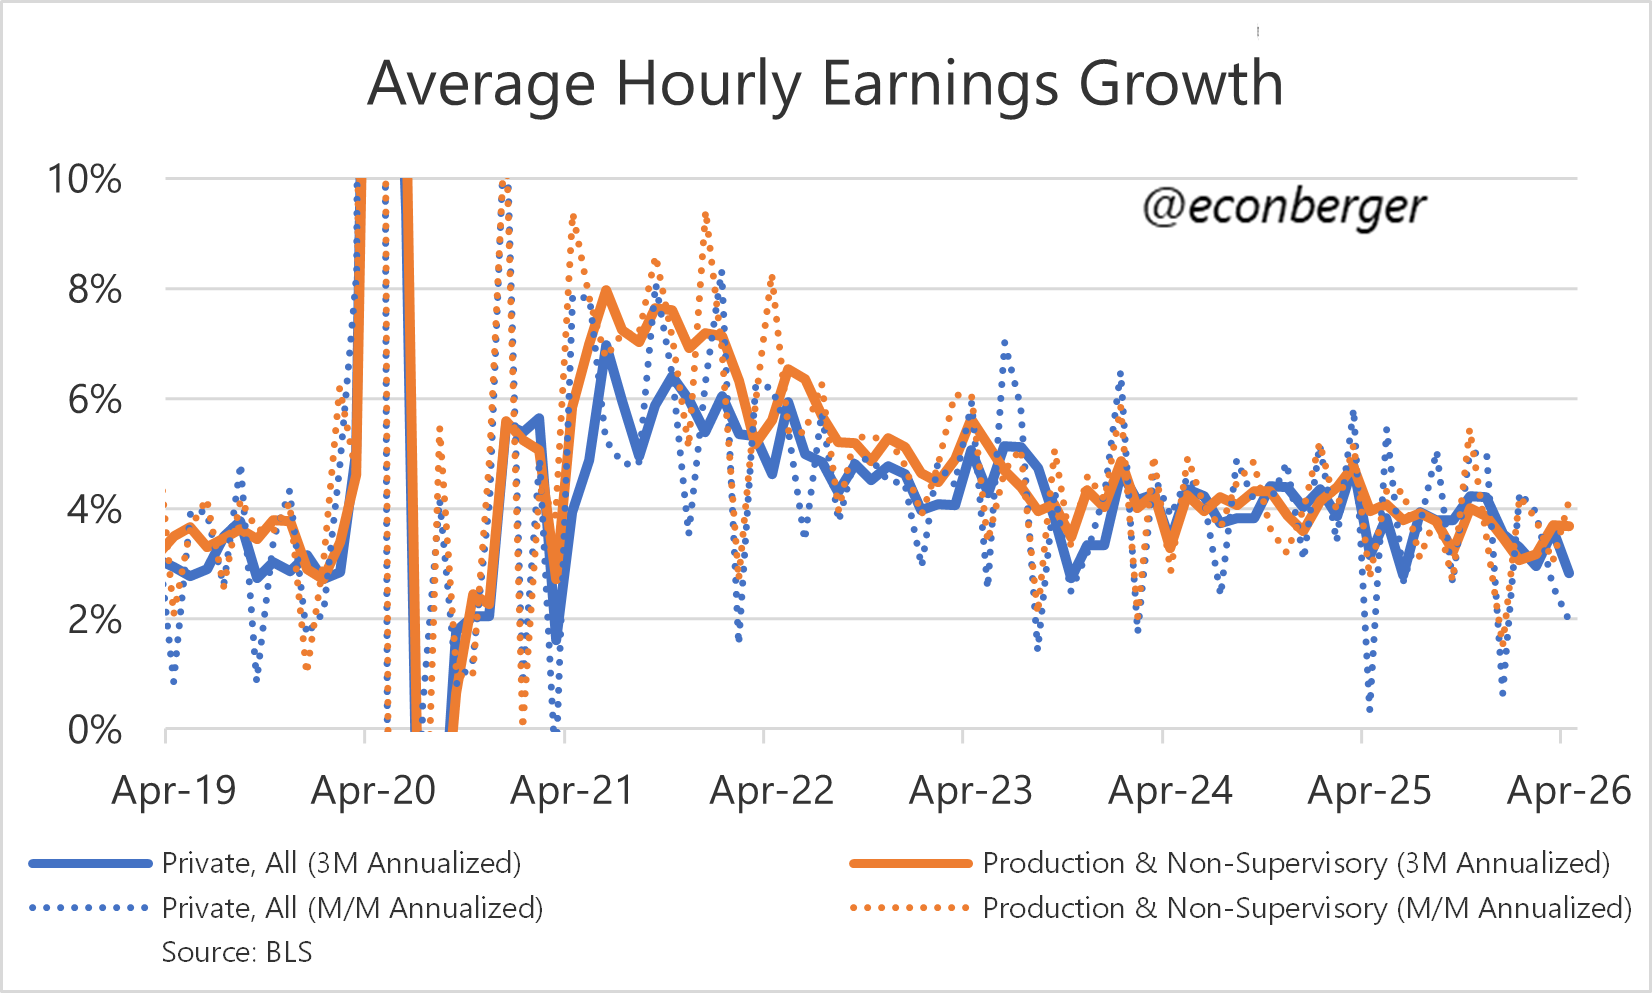
On the wages side, we’re clearly running at a lower growth pace than 6 months ago. But the ECI data showing faster benefit cost growth may mean that wages are painting an overly rosy picture of labor market disinflation:
Now onto the household survey. The share of prime working age Americans with a job remains quite resilient. Most of the household survey data has a common theme: a little worse in April than in March, a little better than in late 2025. In the case of this indicator, it’s good to substitute “very little” for “a little” on both comparisons.
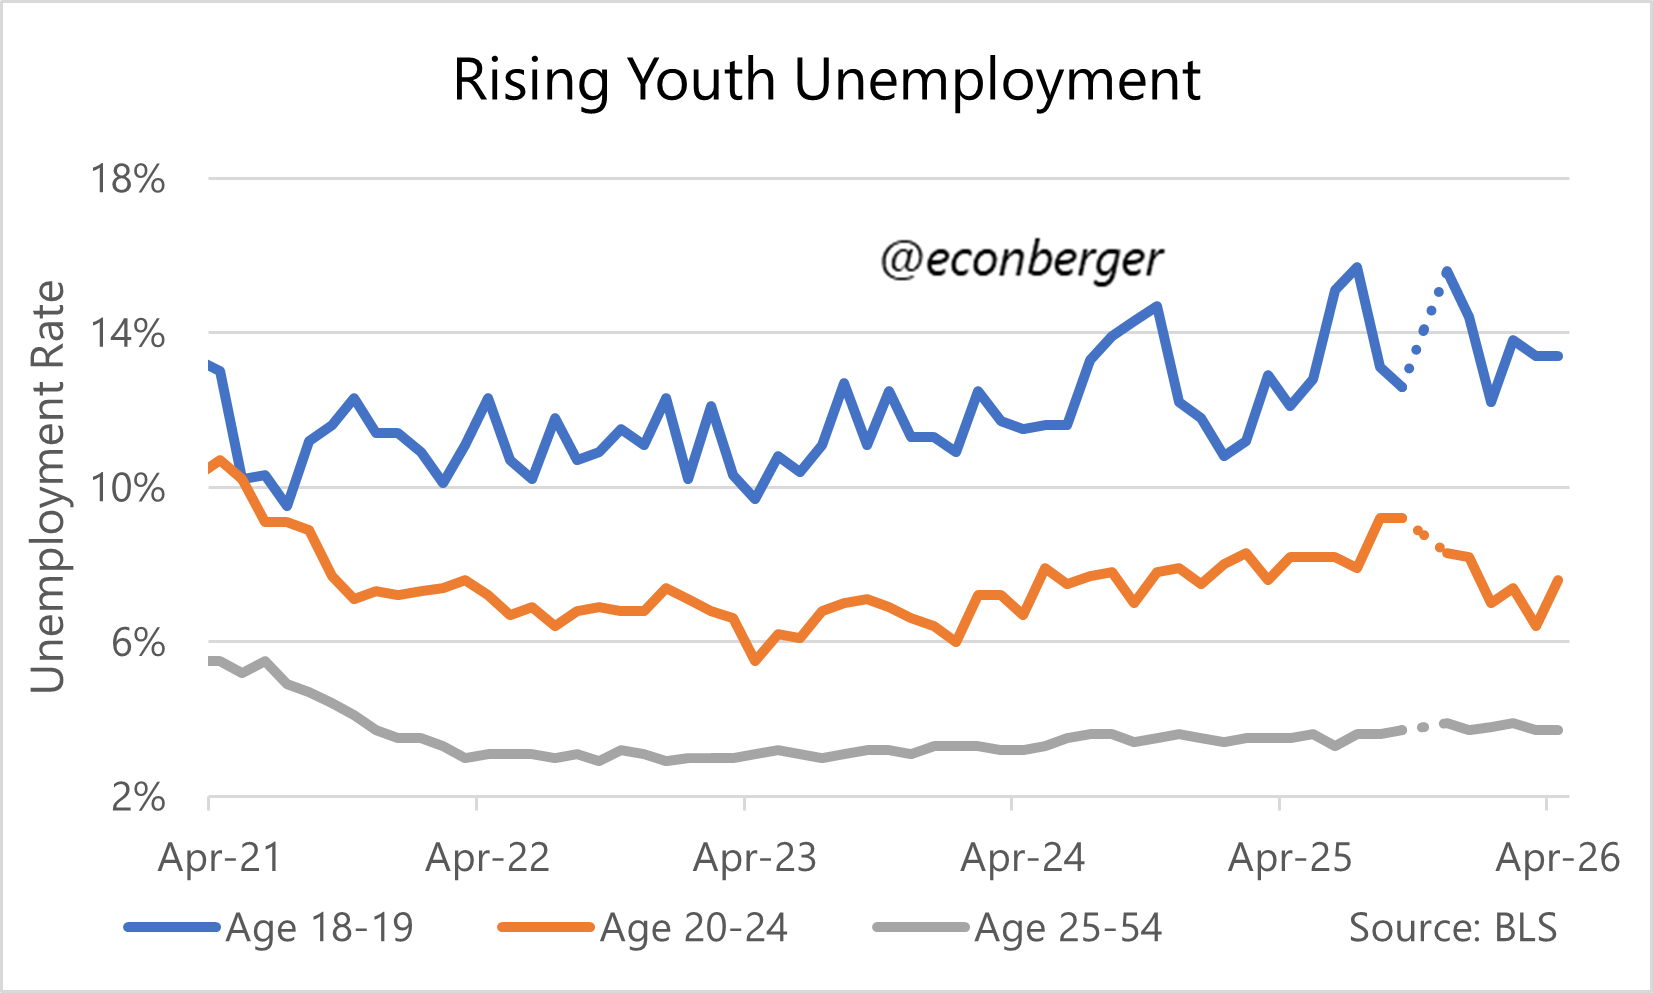
The youth labor market: unemployment for people in their early 20s rose in April, but is quite a bit lower than it was late last year (and slightly lower than it was a year ago). Unfortunately, we have not seen improvement of the same magnitude for workers in their late teens.
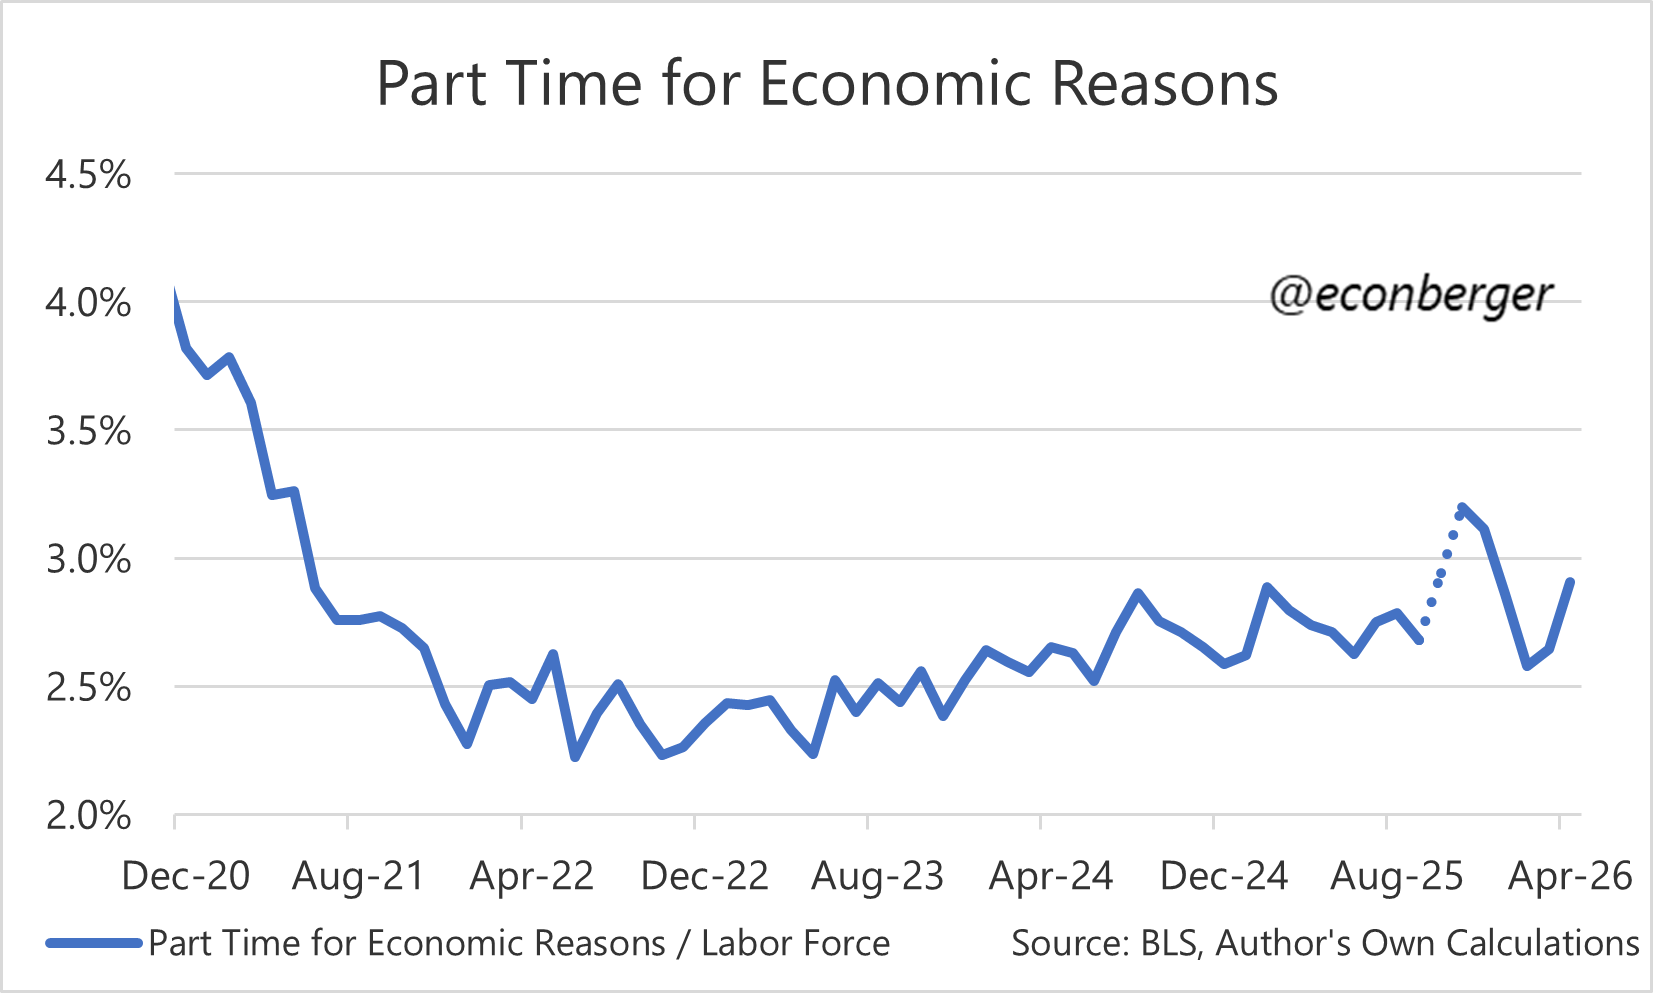
Part-time for economic reasons had been one of the few indicators in the report that showed not only an improvement relative to the fall, but also relative to a year ago. That ended in April with a fairly large increase. I don’t find this to be particularly worrisome - the pace of increase (noise aside) is slow.
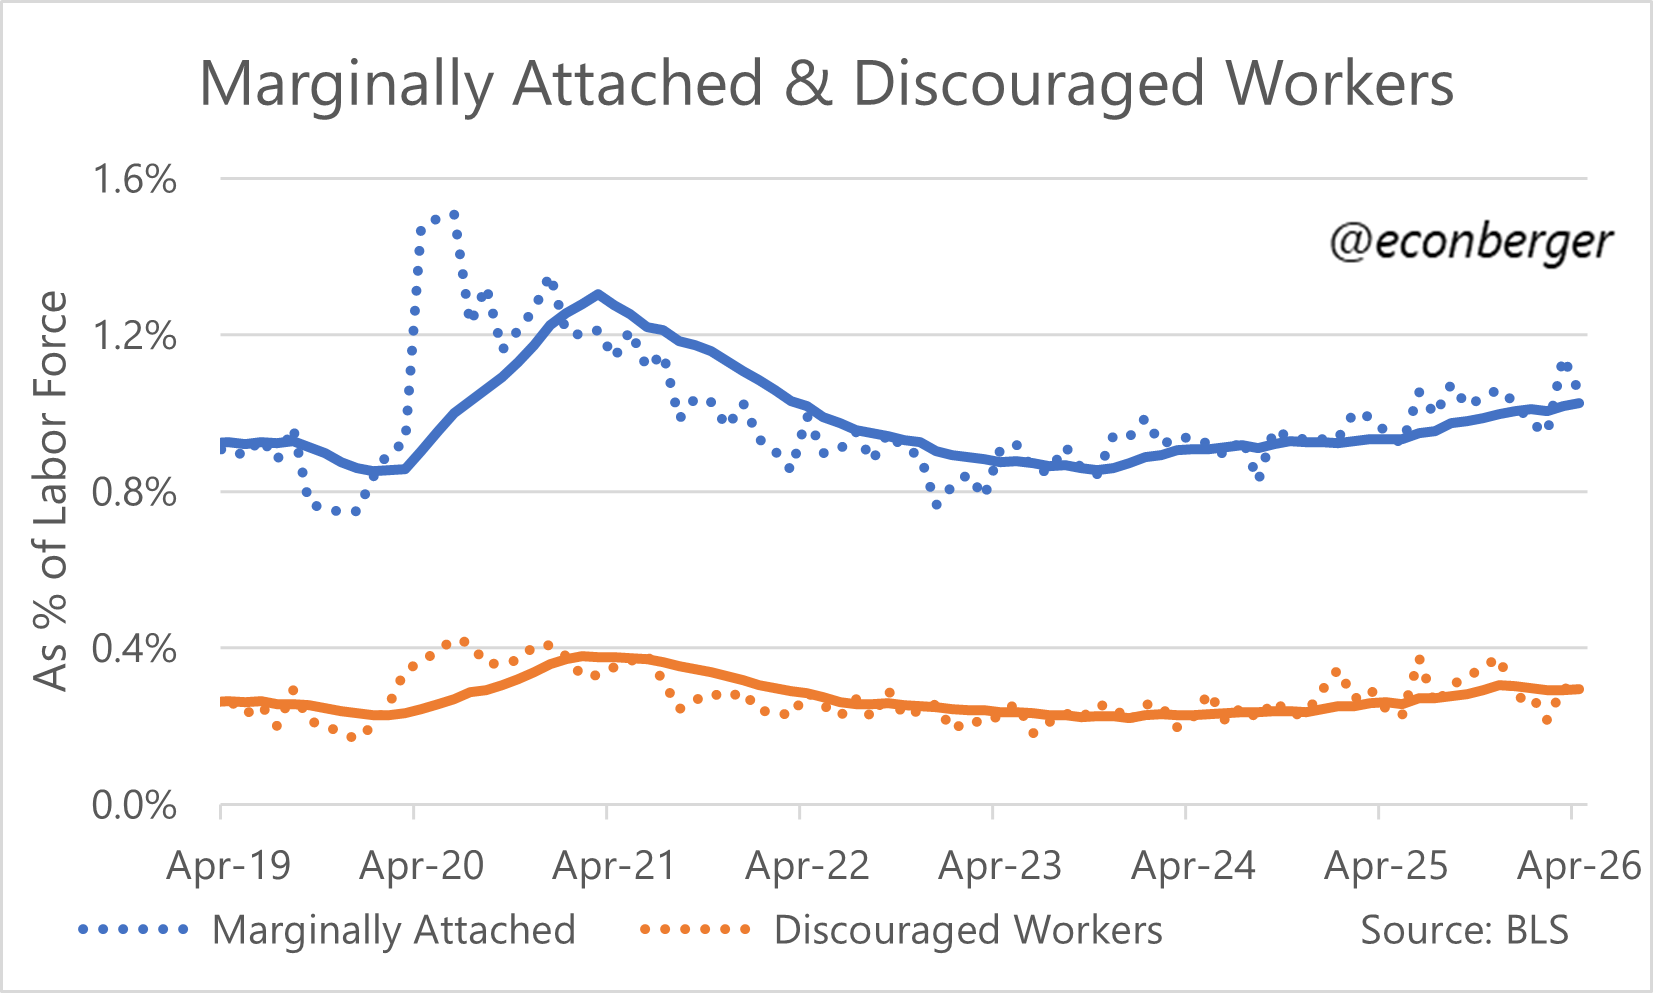
We saw a slight decline in the number of marginally attached workers; these are folks who want a job and are available to work, but aren’t actively looking (so they don’t count as “unemployed”). This was one of the few “upside down” numbers in April’s household survey - as in, it was better in April than in March, but is a little worse than it was in the fall.
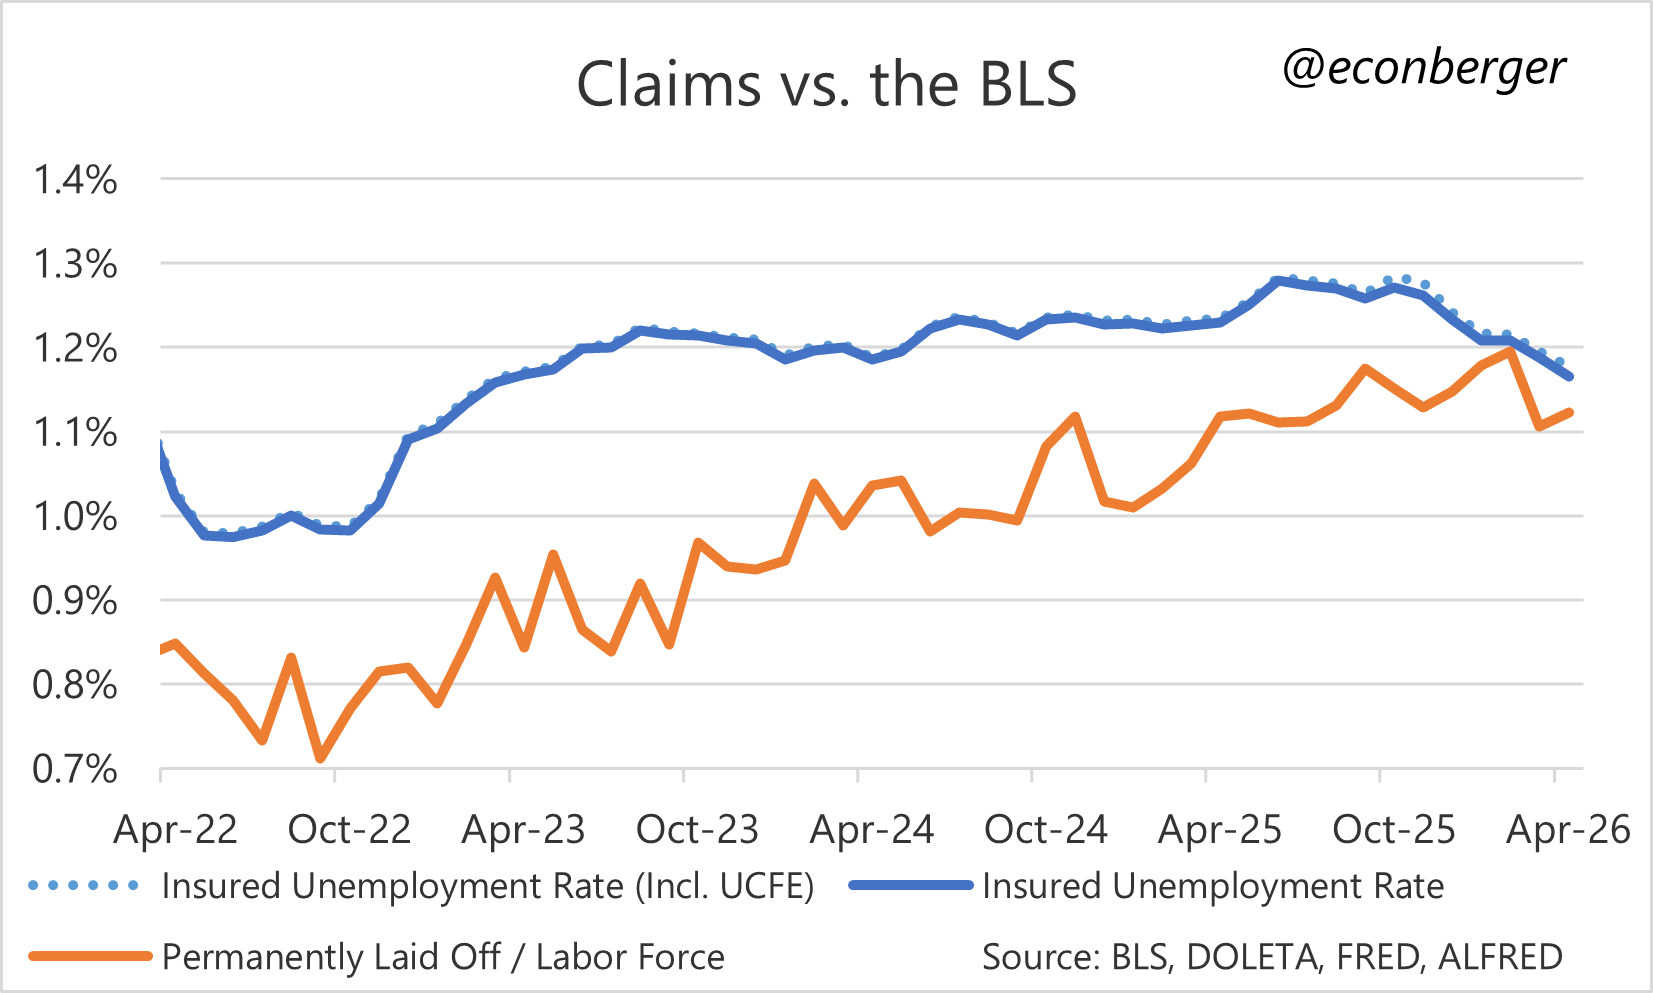
One thing I’d been curious about is whether the improvement in continuing claims would start showing up in unemployment due to permanent layoff. And I think that is emerging - this category was flat in April relative to a year earlier. I don’t know if it will decline outright, but the pace of increase has certainly slowed substantially.
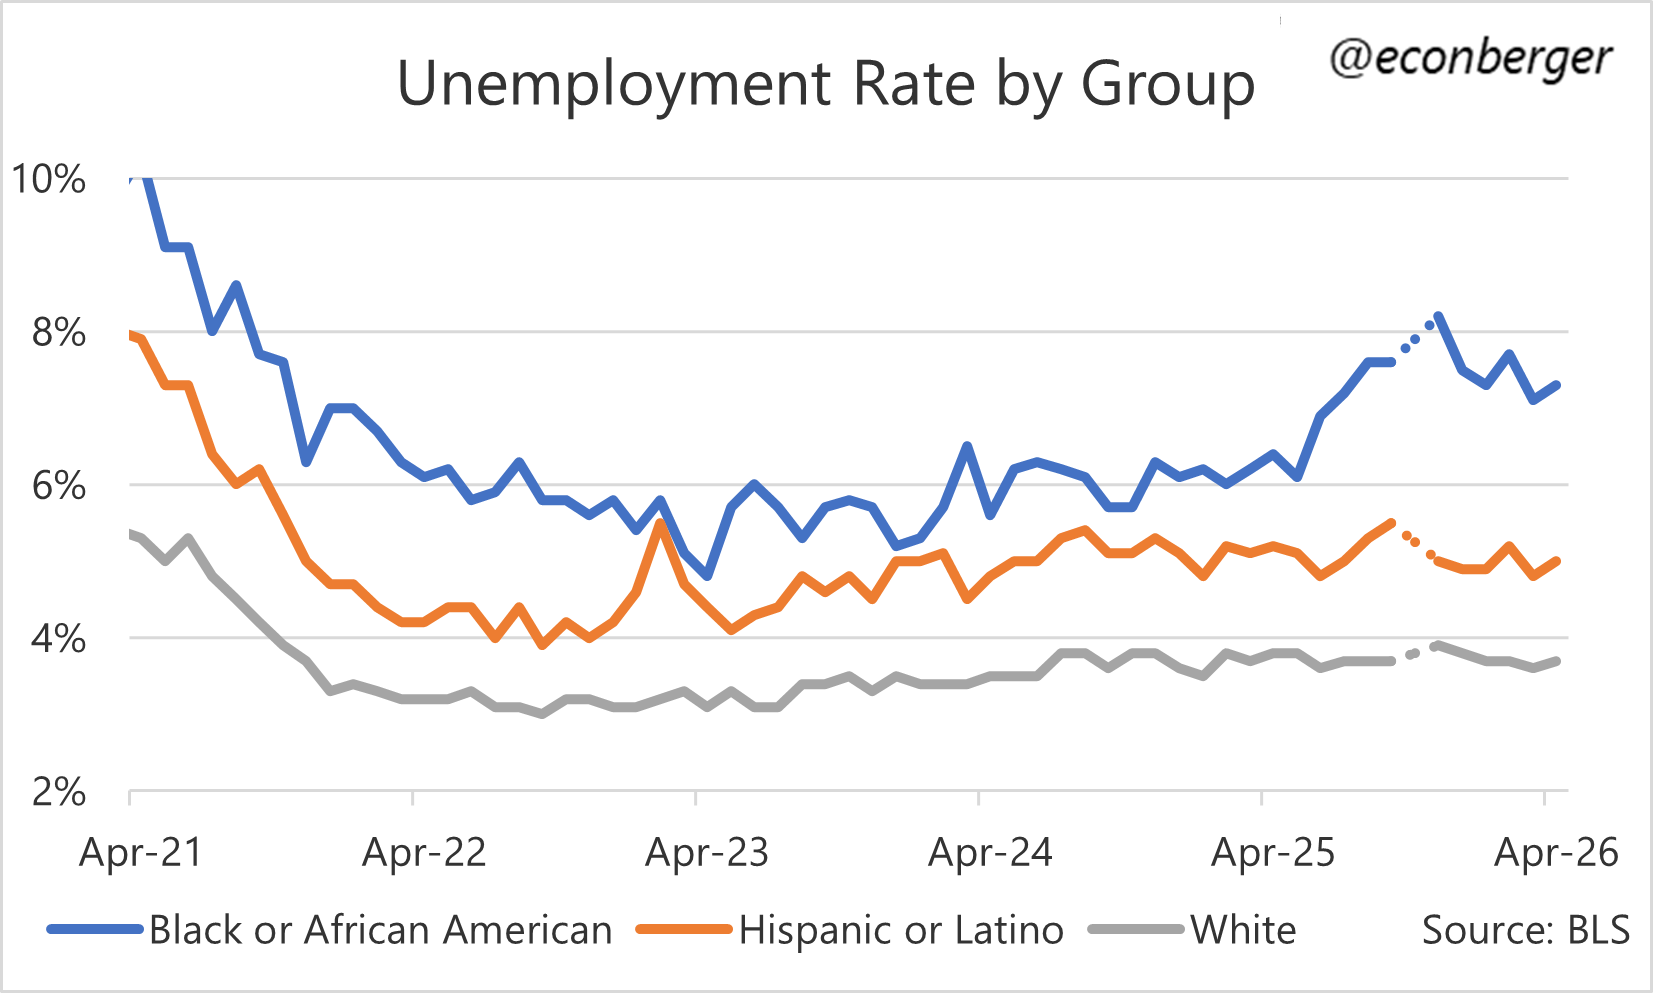
African American unemployment has tracked, with a grimly higher beta, overall unemployment - a big improvement since the fall, but still higher than a year ago and slightly higher in April than in March. Hispanic and white unemployment are down slightly relative to a year ago.
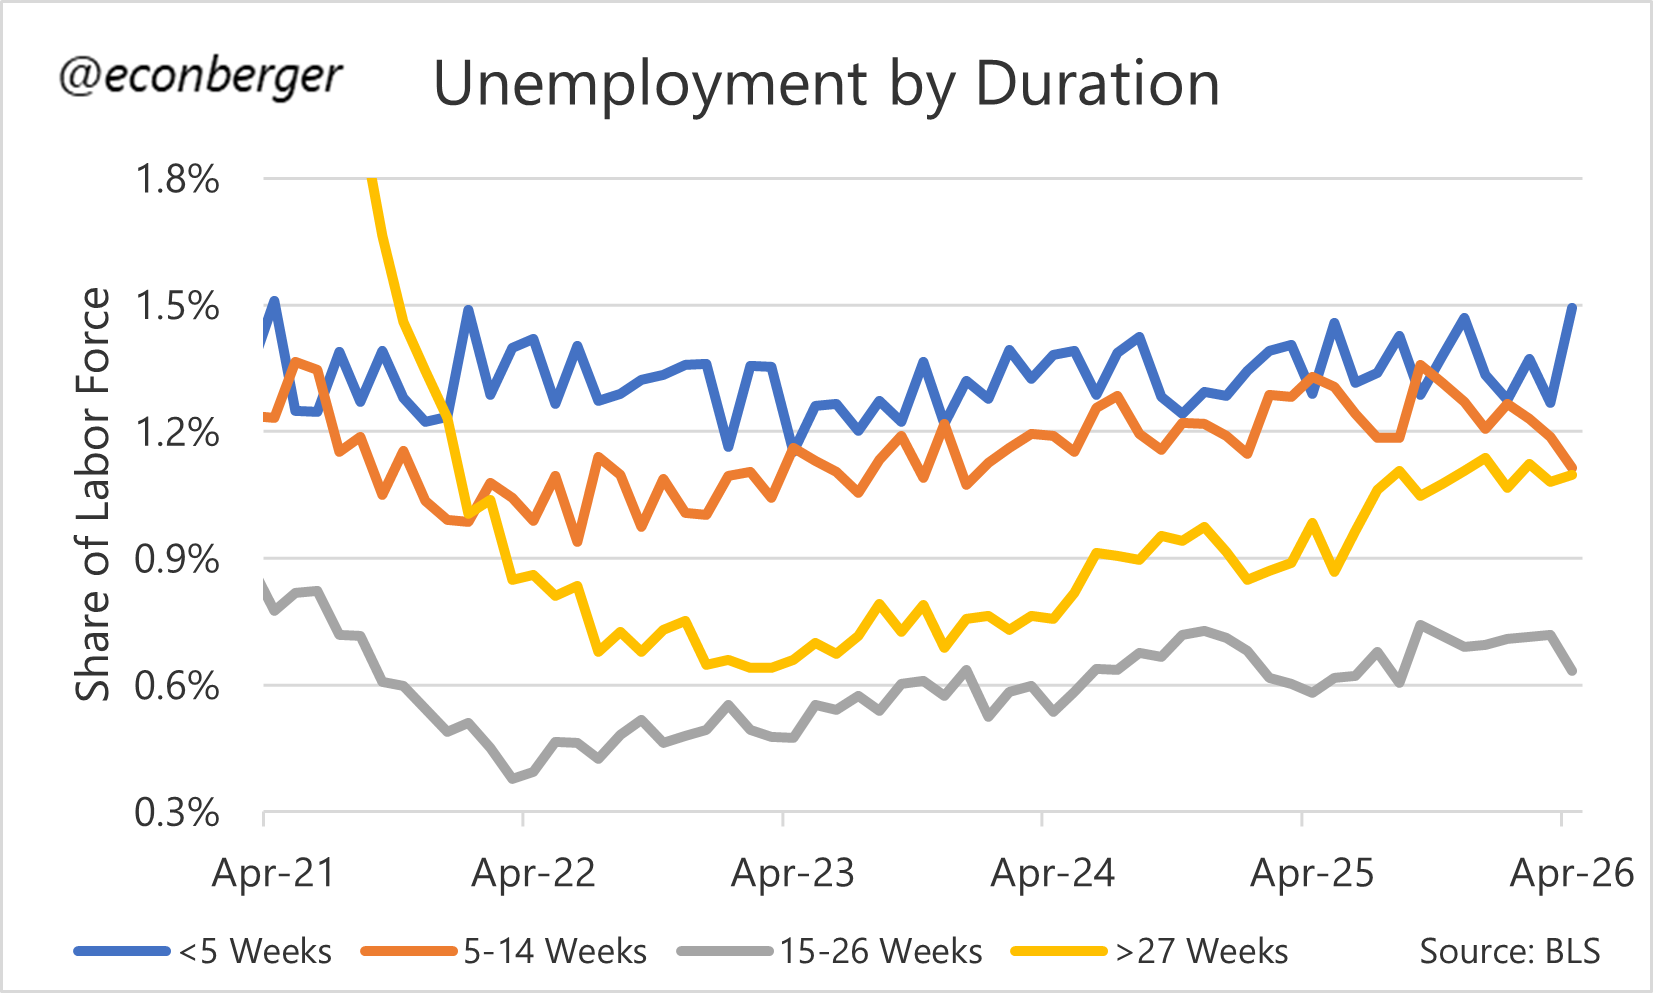
And the number of short- and medium-term unemployed has been flat or even down recently, but the number of long-term unemployed continues to rise. Due to low layoffs relatively few people enter the unemployment pool, but due to low hiring it’s hard to leave.
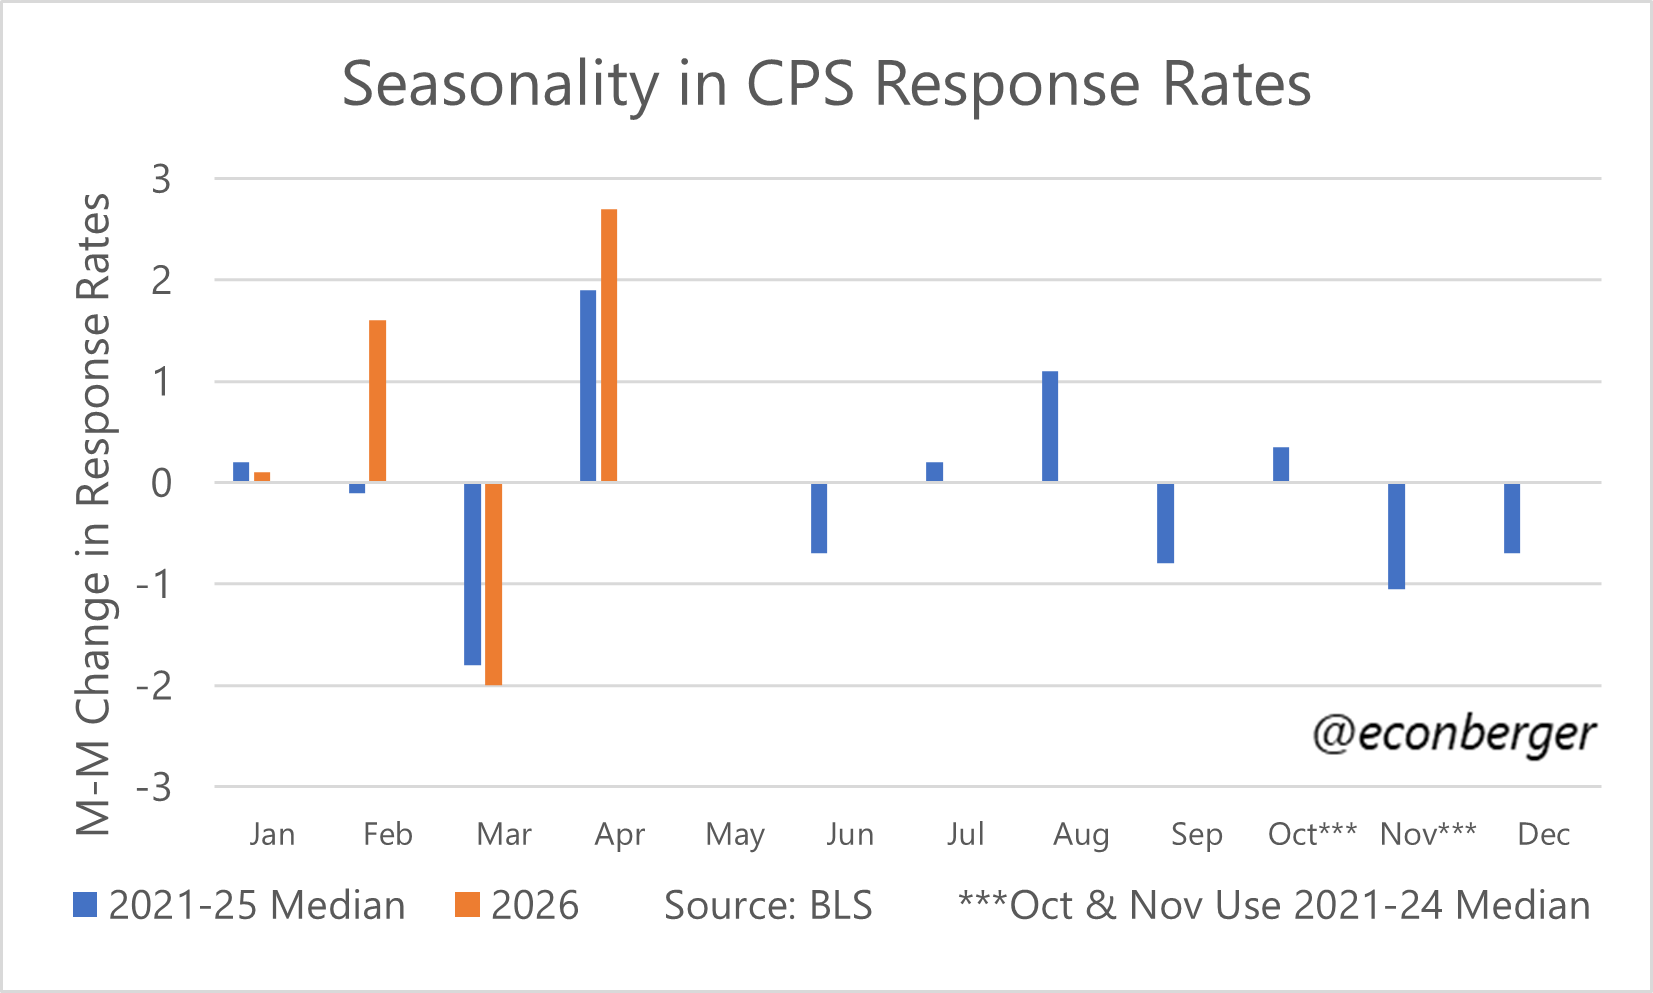
The final chart of the week before it’s 5 o’clock on the west coast - Current Population Survey response rates. They plunged in the aftermath of the shutdown, and took another big step down in March. That led me to look at seasonality, and it seems to be quite significant in March/April! Sure enough, as in prior years, the response rate jumped in April, reveresing its March decline. But it’s still lower than it was a year ago, part of an ongoing gradual decline:
Alright, that’s enough data! See you all next week.
Caution! We know NFP is sensitive to both short-term and long-term revisions.
In a live podcast, the folks at Revelio asked me what I thought payroll gains would be over the remainder of the year. I said 80K… total. i.e. 10K/month. But this is conditional on the Strait of Hormuz remaining a problem.
Thanks Guy! Excellent as always
https://substack.com/@petercorey/note/p-196910818?r=18lysv&utm_medium=ios&utm_source=notes-share-action
Nice recap